Understanding Homeowners Insurance Coverage for Foundation Leaks
Discovering that pressurized plumbing has ruptured beneath your home's foundation is stressful enough without having to navigate confusing insurance policy language. When filing a slab leak insurance claim Tustin homeowners frequently encounter confusing terms regarding what is covered versus what is excluded. The most common question property owners ask is: does homeowners insurance cover slab leaks Tustin?
Please note: this guidance is educational and does not constitute legal or licensed insurance advice. You should always review your specific policy declaration pages and consult your insurance carrier or adjuster directly. However, in California, most standard HO-3 and HO-5 residential policies divide a foundation water leak claim into three distinct operational components:
1. Tear-Out and Access Costs (Commonly Covered)
Under standard open-peril policies, insurance carriers frequently cover the physical labor and demolition required to expose the leaking pipe. This includes jackhammering concrete, removing water-damaged flooring, cutting drywall access, and restoring those structural building components once the plumbing repair is completed.
2. Resulting Water Damage (Commonly Covered)
Sudden and accidental water discharge that damages interior property—such as saturated drywall, ruined carpets, warped engineered hardwood, swollen baseboards, and damaged lower cabinetry—is typically covered under the water damage provisions of your policy, subject to your policy deductible.
3. The Physical Plumbing Pipe Repair (Typically Excluded)
Most insurance policies consider the physical pipe itself to be a maintenance item. Consequently, the isolated plumbing cost of replacing or soldering the failed copper pipe section (typically several hundred dollars) is often paid out of pocket by the homeowner, while the thousands of dollars in access, demolition, drying, and structural restoration are handled by insurance.
Why Professional Diagnostic Documentation Is Essential
Insurance claims adjusters require verifiable technical evidence before approving coverage for access tear-out and water damage restoration. Providing vague or unverified statements often causes claim delays or premature claim denials. That is why professional slab leak documentation Tustin technicians provide is vital to a smooth claims process.
Our comprehensive technical diagnostic package includes:
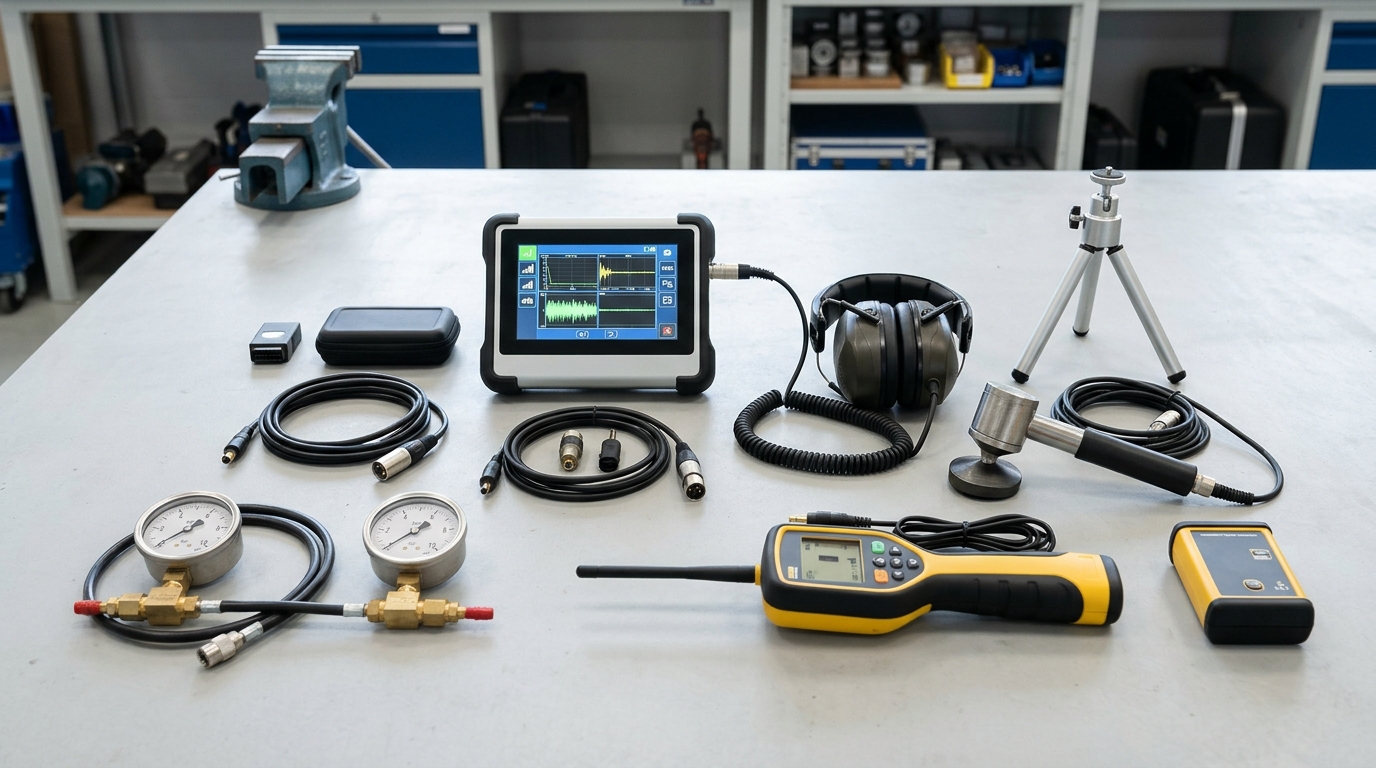
- Written Plumber's Diagnostic Report: A formal itemized document detailing the exact cause of failure (e.g., pressurized subterranean copper line rupture), pipe depth, and line destination.
- Thermal Infrared Imaging Photographs: Radiometric images showing the exact thermal heat footprint and subsurface moisture spread under concrete and floor coverings.
- Calibrated Nitrogen Pressure Test Data: Gauge verification documenting rapid pressure decay, confirming an active, continuous pressurized domestic leak.
- Moisture Mapping Logs: Quantitative non-invasive moisture meter percentages recorded across affected drywall, subfloor framing, and baseboards.
- Itemized Scope Separation: Clear separation between access/tear-out restoration labor and direct pipe plumbing costs so your claims adjuster can process eligible items immediately.
Immediate Steps to Take When You Suspect a Foundation Leak
Protecting your property and your insurance rights requires prompt, methodical action:
- Mitigate Further Damage: Shut off the main water valve immediately to stop continuous water loss into the subgrade. Homeowners have a policy duty to take reasonable steps to prevent further property damage.
- Take Timestamped Photos and Videos: Document all visible standing water, lifted floorboards, discolored drywall, and water meter movement before any demolition begins.
- Schedule a Professional Electronic Detection: Call our team at (888) 205-7875 to conduct formal non-invasive slab leak detection and generate your written report.
- Notify Your Insurance Carrier: Open an insurance claim and provide your adjuster with the written diagnostic report and thermal imagery.
- Evaluate Overhead Reroute Feasibility: Ask your adjuster if your policy covers the cost of an overhead reroute. In many cases, carriers prefer an overhead slab leak reroute because it eliminates the massive expense of jackhammering and restoring interior finished flooring.
Exploring Permanent Solutions: Reroute vs. Repiping
If your insurer covers structural tear-out, you may choose to invest your insurance payout toward a permanent upgrade rather than patching aging pipes that will leak again. Learn how our whole-house repiping service completely removes leak risk by installing modern PEX-a piping throughout your home. For comprehensive foundation solutions, return to our main slab leak repair in Tustin overview.
Frequently Asked Questions About Slab Leak Insurance Claims
Will my insurance policy pay for an overhead reroute instead of breaking concrete?
Many insurance adjusters readily approve an overhead PEX reroute because bypassing the pipe through the attic costs significantly less than jackhammering through expensive porcelain tile, hardwood, and solid concrete slabs.
What is the difference between sudden water damage and gradual leakage?
Homeowners policies generally cover "sudden and accidental" water escape. Insurers may scrutinize or deny claims if there is evidence of long-neglected rot or leaks that persisted for months without remediation. Prompt professional detection proves when the failure occurred.
Do I have to use the insurance company's preferred plumbing contractor?
No. Under California law, homeowners have the legal right to hire any licensed, qualified plumbing professional they trust to inspect, detect, and repair their property's plumbing system.